
The Golden Month for Precious Metals and AI Infrastructure
As oil prices began stabilising from their April highs, although remaining elevated, CTAs and other systematic traders were already moving towards new opportunities. The commodity rally had expanded beyond oil.
Gold and silver were among the first beneficiaries. As traditional safe haven assets, both metals strengthened alongside the oil price shock. CTAs that had captured the precious metals rally earlier in the year were well positioned. However, an even more significant structural story was developing within industrial metals.
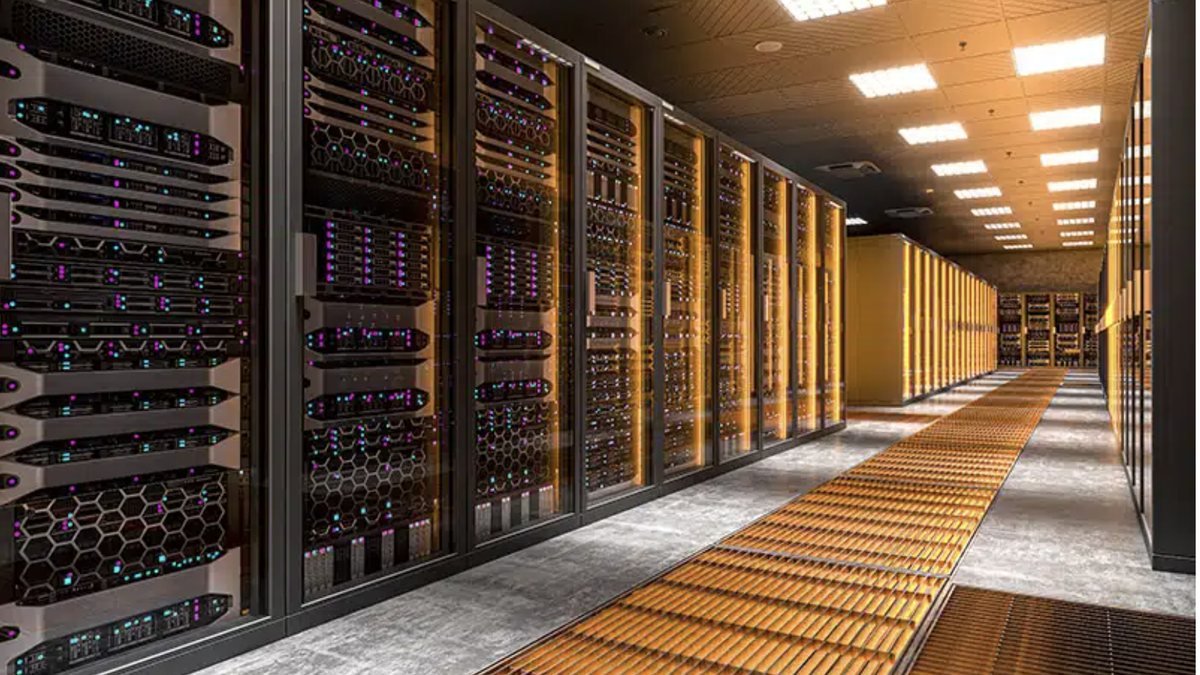
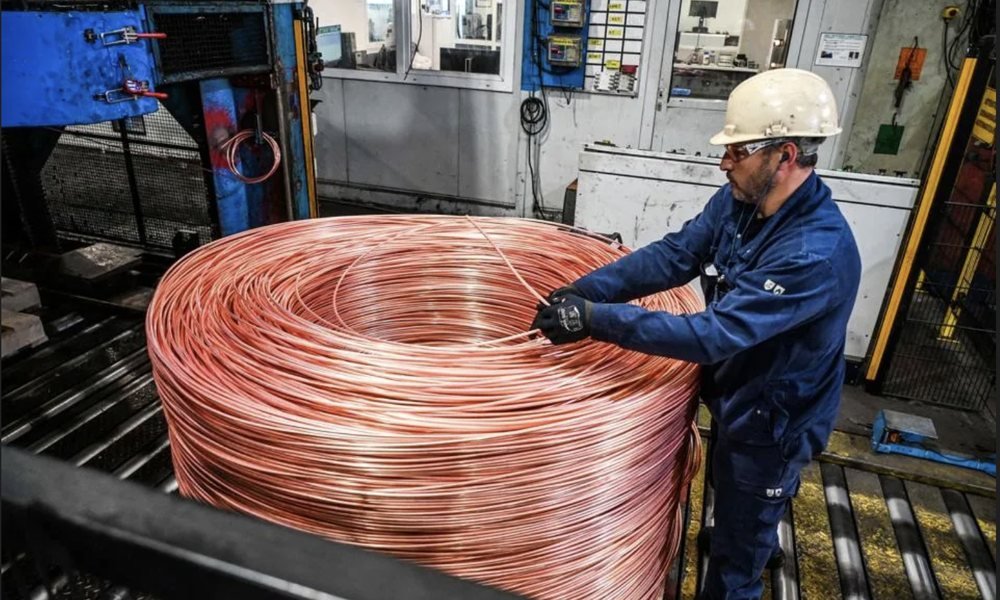
The AI infrastructure investment cycle had been building for months. Data centres require enormous quantities of copper for electricity transmission, power distribution and cooling infrastructure. By May 2026, the market was increasingly recognising that this was not simply a short term technology trend but a structural change in commodity demand.
Razvan Remsing, chief product strategist at Aspect Capital, noted that the potential disruption to global energy supply was greater than in previous shocks, while volatility remained comparatively suppressed because optimism surrounding AI continued supporting risk assets despite growing concerns over future energy supply.
The copper thesis was compelling:
Supply constraints: The copper industry was not discovering and developing enough future mines. S&P Global found that 162 of 258 major copper discoveries made between 1990 and 2024 remained undeveloped.
Development timelines: The average period between copper discovery and production is approximately 17 years and can be even longer for projects initiated after 2025.
Demand growth: AI data centres, electrification and defence spending were all creating additional sources of copper demand.